 by Kenny Lee
Who this article is for: HDB upgraders and private homeowners comparing suburban new launch and resale condos in Singapore, especially buyers deciding whether a higher asking price is justified and owners planning their next sale and purchase.
Reviewed 4 October 2026. News context: URA’s 1 October 2026 Q3 flash estimate. The figures are preliminary; the analysis and hypothetical examples below are FindSpace’s own interpretation, not a valuation or price forecast.
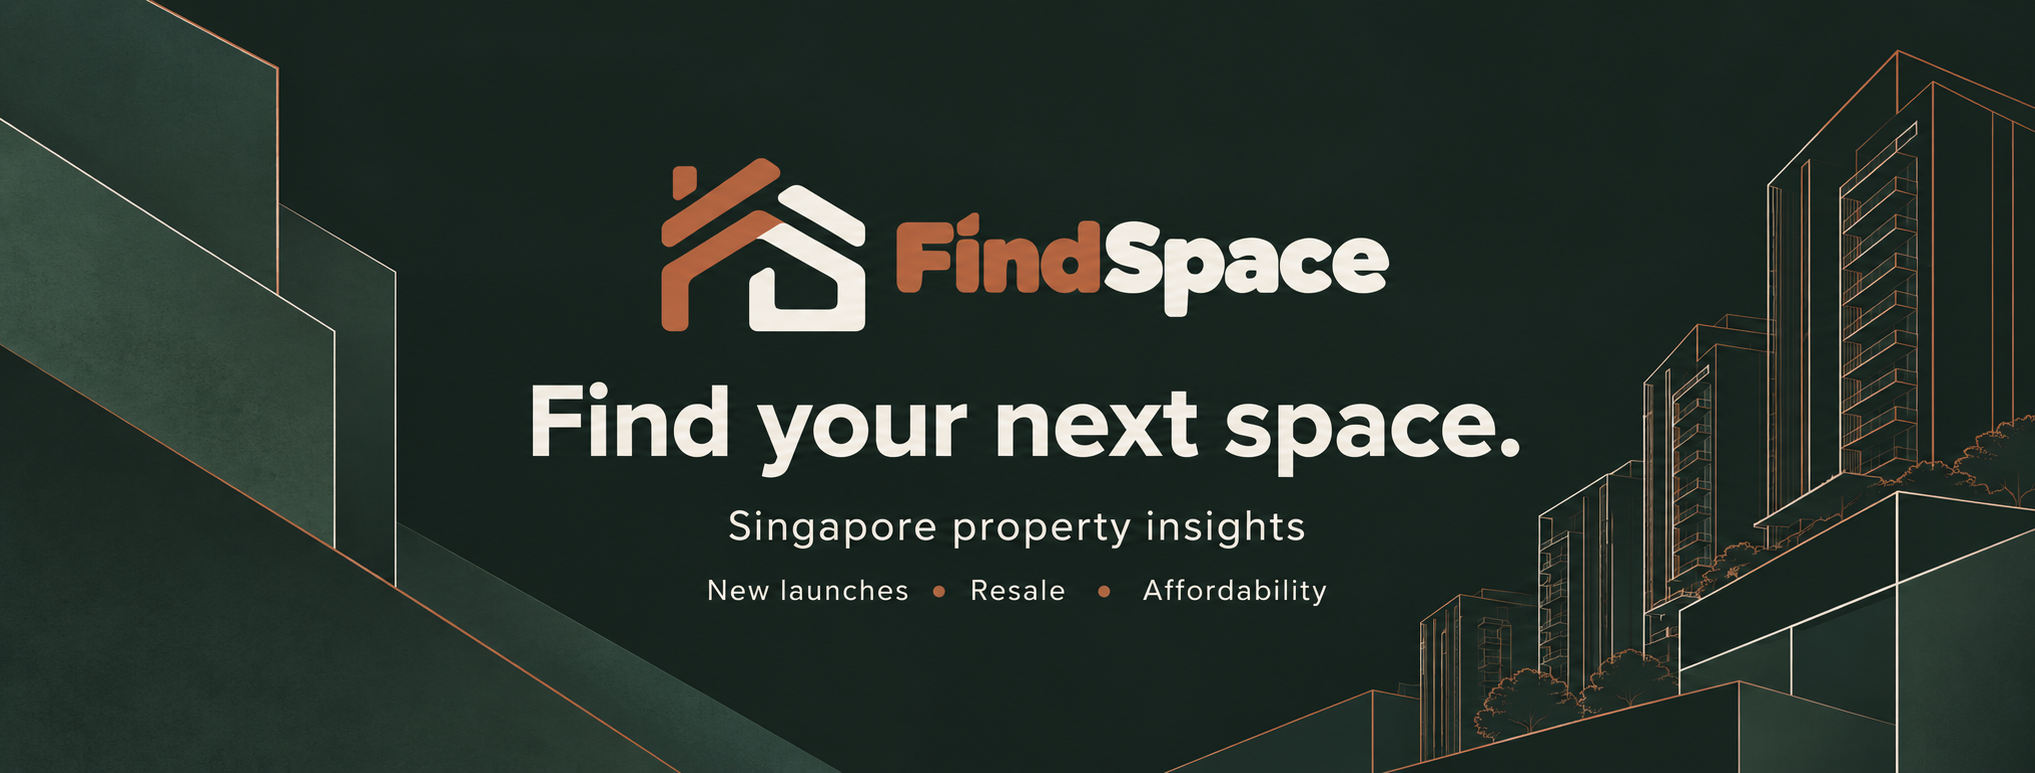
FINDSPACE · VISUAL GUIDE
Hypothetical mortgage scenarios
OCR Condo Prices Rose 2.2%: How Much New Launch Premium Should You Pay?
01
S$1.6m home; S$1.2m loan
Monthly repayment at 3%About S$5,691
Monthly repayment at 5%About S$7,015
02
S$1.8m home; S$1.35m loan
Monthly repayment at 3%About S$6,402
Monthly repayment at 5%About S$7,892
Illustrative FindSpace calculations: fully amortising loans, monthly payments and constant nominal rates. Rates are assumptions, not bank offers. Fees and future rate changes are excluded. See the article for full assumptions.
Calculations: FindSpace. Information source: MoneySense: home-loan context
Original FindSpace infographic · AI-assisted design. Article date: 2026-10-04. Visual added 4 October 2026.
The OCR condo premium question after the latest price update
A stronger suburban property index can make a higher condo asking price feel reasonable. That feeling is a poor substitute for evidence. The useful question is how much extra you are paying for the exact home, what that premium buys, and whether your household can carry it through a less favourable market.
In its 1 October release, URA estimated Q3 private residential prices rose 1.4% overall. Non-landed prices rose 0.9%; their regional changes were +2.2% in the Outside Central Region (OCR), +0.2% in the Rest of Central Region and −0.1% in the Core Central Region. These are preliminary regional measures, not individual condo valuations.
URA reported 4,296 sale transactions up to mid-September against 6,148 in Q2, describing a decline of about 30%. This early count is not a final, full-quarter comparison. The flash estimates use available stamp-duty and developer-sales data up to mid-September; URA’s full Q3 statistics are due on 23 October and may revise the estimates.
FindSpace’s interpretation: use the update to revisit your comparisons, while requiring unit-level evidence before raising an offer. It does not establish that today’s launch premium will be recovered when you sell.
Start with a matched comparison, not a district average
Build a shortlist around the buyer’s real alternatives. A family needing three usable bedrooms near a particular transport route should compare homes satisfying that requirement, rather than every condominium in the district. A cheaper apartment with an unsuitable third room is not a meaningful substitute.
For each candidate, record total price, stated area, bedroom and bathroom configuration, tenure and lease commencement, floor, facing, condition, maintenance charges and likely move-in date. Separate recorded transactions from asking prices. Also separate developer sales, sub-sales and ordinary resale deals, since their circumstances can differ.
Review the floor plan and measurement basis before treating a psf gap as a discount. Two homes with similar advertised areas can provide different usable space. Ask where wardrobes, storage and work areas fit, and whether daily circulation depends on passing through another room. Compare the actual unit’s balcony, air-conditioning ledge and other area components where applicable.
Use several relevant transactions where available. If evidence is sparse, describe the uncertainty instead of selecting the single sale that supports your preferred conclusion. A valuation discussion should explain adjustments for condition, layout and floor, not hide them inside a confident headline price.
What can justify paying more for a new launch?
A premium can purchase benefits that matter to a specific household: a workable layout, a preferred facing, newer building systems, facilities or a completion timeline matching a planned move. Assign priorities before visiting the showflat so presentation does not decide the budget for you.
Test each benefit against alternatives. If direct transport access is the main attraction, compare the actual walking route and your commuting pattern. If facilities are important, consider how frequently you will use them and the ongoing maintenance commitment. If the purchase is mainly an investment, evaluate realistic tenant needs rather than assuming your own preferences represent rental demand.
The test is whether the benefits remain valuable at the extra total quantum. A desirable feature can still be overpriced. Write down which features are essential, which are optional and the maximum extra amount you are willing to pay. This helps distinguish a considered lifestyle choice from a return assumption.
A S$200,000 premium has a monthly cost
Consider two entirely hypothetical homes priced at S$1.6 million and S$1.8 million. Suppose, solely for comparison, borrowing equals 75% of each price: S$1.2 million and S$1.35 million. This is a modelling assumption, not a statement that either loan is available or that every buyer qualifies for that percentage.
| Hypothetical price and loan | Monthly repayment at 3% | Monthly repayment at 5% |
|---|---|---|
| S$1.6m home; S$1.2m loan | About S$5,691 | About S$7,015 |
| S$1.8m home; S$1.35m loan | About S$6,402 | About S$7,892 |
FindSpace calculations: fully amortising loans over 25 years, monthly payments, constant nominal annual interest divided by 12, rounded to whole dollars. The rates are hypothetical, not current bank quotations or regulatory assessment rates. Fees and future rate changes are excluded.
The higher-price scenario requires S$50,000 more equity before duties and other expenses, plus roughly S$711 more each month at 3%, or S$877 at 5%. The larger loan’s repayment rises by about S$1,490 between the two rate scenarios. Ask whether that burden fits alongside childcare, retirement saving and an emergency reserve.
For a home under construction, obtain the applicable payment schedule and model both interim payments and the eventual full loan. A comfortable early instalment does not establish comfort after completion. Include existing housing costs and temporary accommodation when the timelines overlap.
HDB upgrading: calculate the money you can actually deploy
An HDB-to-condo upgrade can suit a household with stronger finances and changed housing needs. It should improve something specific—space, location, facilities or a long-term ownership plan—while preserving enough flexibility to withstand setbacks. Remaining in the current flat is a valid comparison when an upgrade would consume essential reserves.
CPF Board explains that sale proceeds generally repay the outstanding housing loan and refund CPF used for the property, including accrued interest. For older members, applicable retirement requirements affect the refund’s treatment. Check your own CPF housing refund position; a headline sale price is not your available cash.
Make a dated funds schedule: deposit, duties, legal fees, sale completion, loan drawdown, renovation and moving. Identify which amounts must be cash and which CPF funds are available for use. Verify flat-specific eligibility and occupation restrictions with HDB, and obtain a written financing assessment before committing. Buying first and selling first have different cash-flow risks.
A second property needs its own investment case
If the plan is to retain an existing home, acquisition costs become especially important. IRAS currently lists 20% ABSD for a Singapore citizen buying a second residential property. On a hypothetical S$1.8 million taxable value, that is S$360,000, before other acquisition expenses. Ownership profile and any relief conditions must be checked individually; do not assume a remission applies.
Test rental income after vacancy, maintenance, repairs, taxes and financing costs. Compare the outcome with retaining liquid reserves or reducing debt. A second unit that absorbs every spare dollar can weaken the household even if its advertised gross yield looks attractive. Two homes in the same market also do not remove concentration risk.
Refinancing improves financing; it cannot validate the purchase price
MoneySense advises regular loan reviews, particularly after lock-in. Compare repricing with your current lender and refinancing elsewhere, allowing for penalties, clawbacks, legal fees and the new lock-in. Assess savings over your likely holding period rather than focusing only on the advertised rate.
A smaller principal reduces borrowing because you use additional funds or borrow less. A longer tenure can reduce instalments but may increase total interest and remain subject to eligibility. Keep these choices separate from rate savings. If a purchase only works with repeated refinancing at ever-lower rates, revise the purchase budget instead of treating future refinancing as assured.
Plan the resale audience before paying the premium
Describe who could realistically buy the home from you later: a nearby upgrader, a family needing the layout or a buyer anchored to the location. Then ask which competing homes that audience could choose. Include similar units within the development, surrounding resale condos and potential future alternatives without predicting their prices.
For an investment, model a flat sale-price scenario after selling costs and financing expenses. For own stay, ask whether you would still value the home if resale takes longer than expected. Neither a regional index gain nor an attractive showflat answers those questions.
Owners considering consolidation or retirement right-sizing should use the same discipline: net proceeds, replacement costs, accessible housing and reliable cash flow. A bigger home can improve lifestyle while reducing liquidity; a smaller home can release resources without making all sale proceeds freely spendable.
Your decision before the final Q3 release
Prepare three things now: a matched transaction comparison, a dated cash-flow plan and a written maximum offer. Review them when fuller data becomes available. Waiting for another headline is less useful than knowing which fact would actually change your decision.
Read our new launch versus resale condo planning guide and Q3 flash-estimate summary. DM us to compare your shortlisted unit’s premium, affordability and likely exit audience.
Sources and disclaimer
Sources reviewed on 4 October 2026: URA, Q3 2026 flash estimate, published 1 October 2026; IRAS ABSD guidance; MoneySense home-loan guidance; and CPF Board housing-refund guidance.
This article provides general information and FindSpace’s analysis, not personalised financial, investment, mortgage, legal or tax advice or a recommendation to transact. Preliminary statistics may be revised. Examples are hypothetical and do not represent available units, bank offers, loan approvals, valuations or guaranteed returns. Prices, rates, taxes and eligibility can change. Verify requirements with the relevant authorities, lender and qualified advisers, and assess your own affordability, liquidity and retirement needs before committing.